The Courtyard
Six-page illustrative appraisal. Fictional assumptions. Not a formal valuation or lending decision.
Download sample PDF ↓01. The opportunity at a glance
Read this page as text
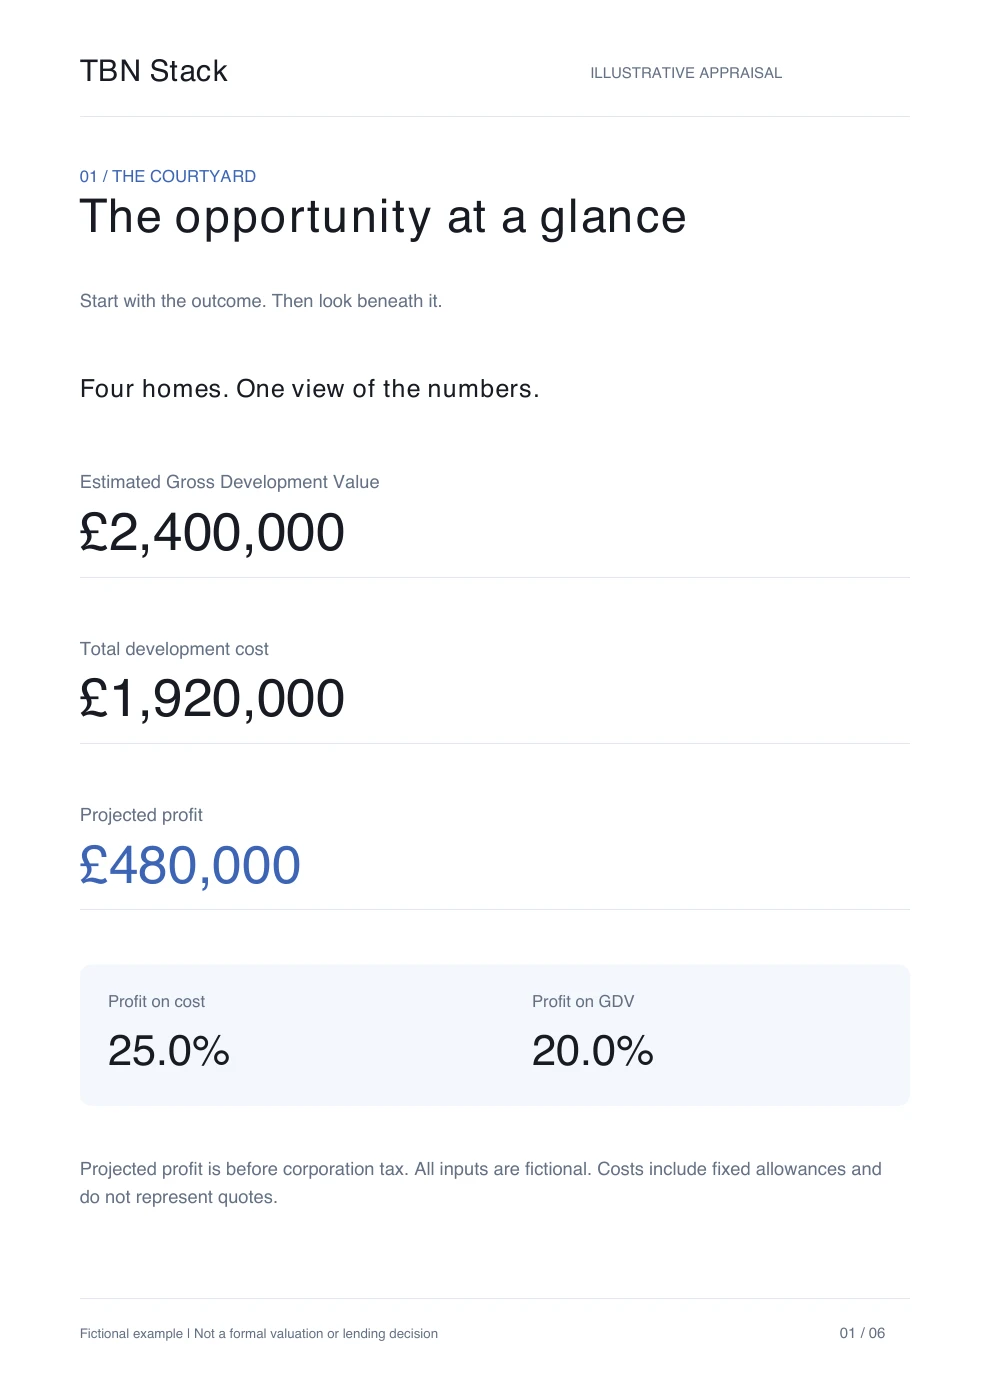
Estimated Gross Development Value: £2,400,000
Total development cost: £1,920,000
Projected profit: £480,000
Profit on cost: 25.0%. Profit on GDV: 20.0%.
Projected profit is before corporation tax. All inputs are fictional. Costs are fixed allowances, not quotes.
02. The scheme and sales values
Read this page as text
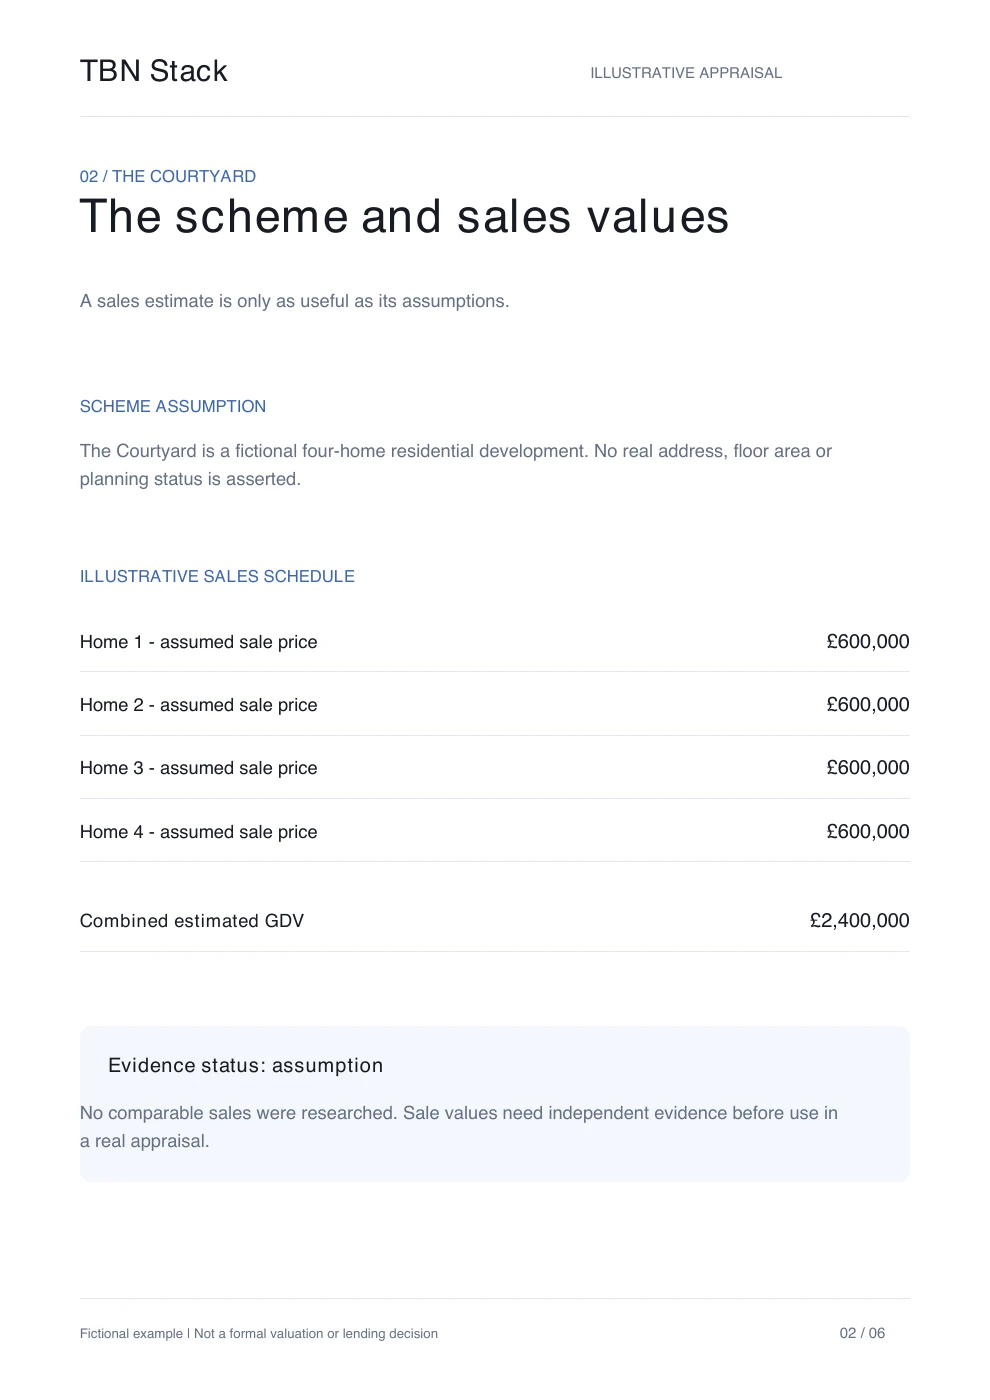
Fictional four-home residential development. No real address, floor area or planning status is asserted.
Homes 1, 2, 3 and 4: £600,000 assumed sale value each. Combined GDV: £2,400,000.
No comparable sales were researched. Independent evidence is required.
03. Where the money goes
Read this page as text
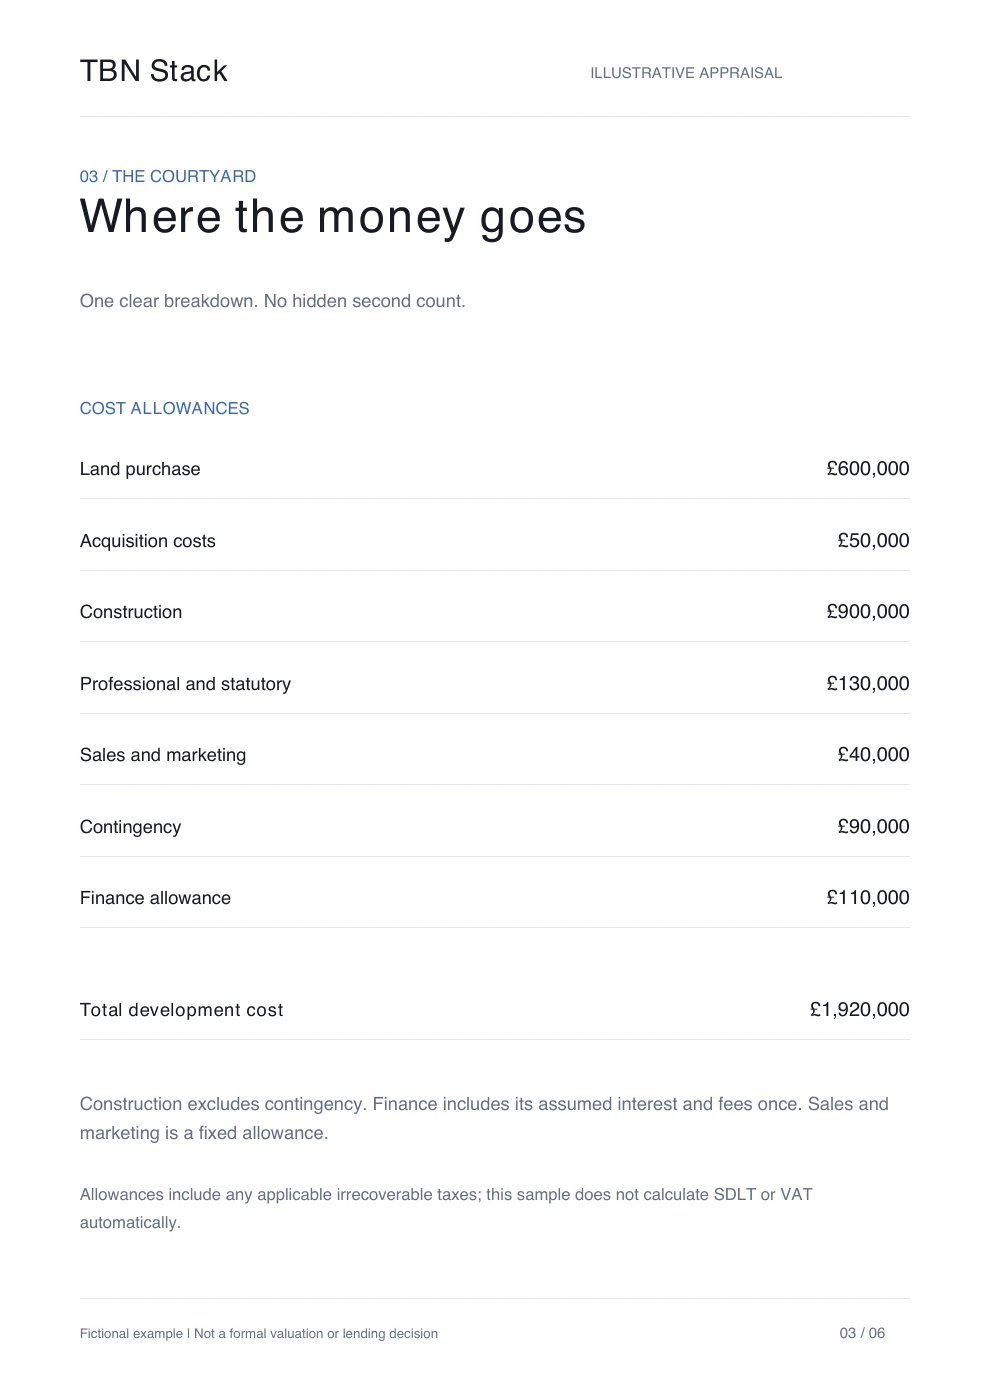
Land purchase: £600,000
Acquisition costs: £50,000
Construction: £900,000
Professional and statutory: £130,000
Sales and marketing: £40,000
Contingency: £90,000
Finance allowance: £110,000
Total development cost: £1,920,000
Construction excludes contingency. Finance includes assumed interest and fees once. Fixed allowances include applicable irrecoverable taxes; no automatic SDLT or VAT calculation.
04. Finance, with context
Read this page as text
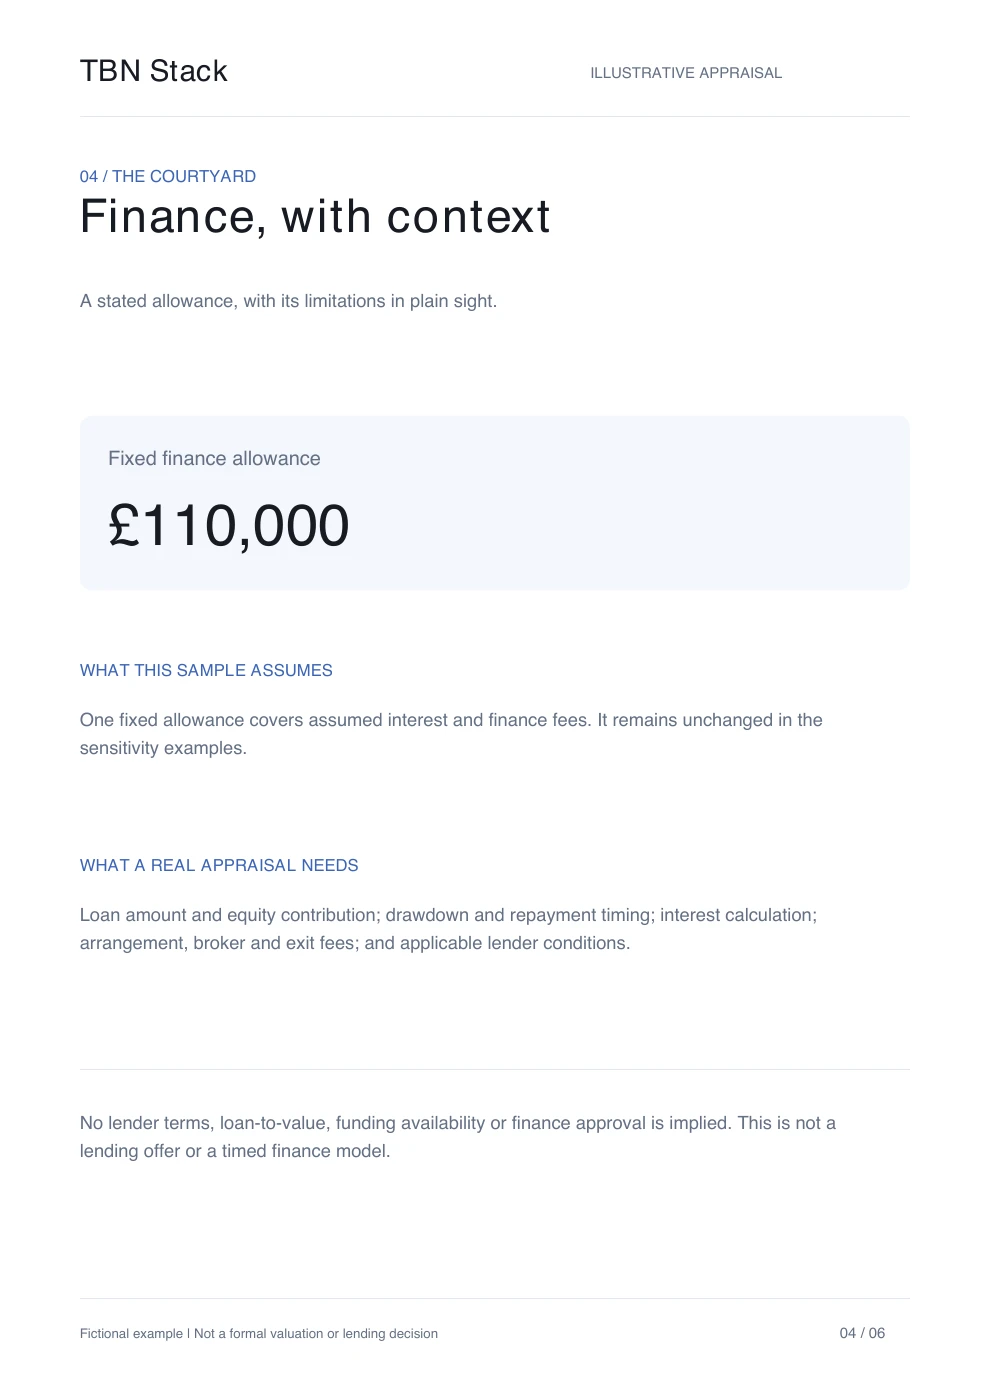
Fixed finance allowance: £110,000. Includes assumed interest and finance fees, unchanged in sensitivity examples.
A real appraisal needs loan amount, equity, drawdown and repayment timing, interest calculation, fees and lender conditions.
No lender terms, loan-to-value, availability or approval is implied. Not a lending offer or timed finance model.
05. What if the figures change?
Read this page as text
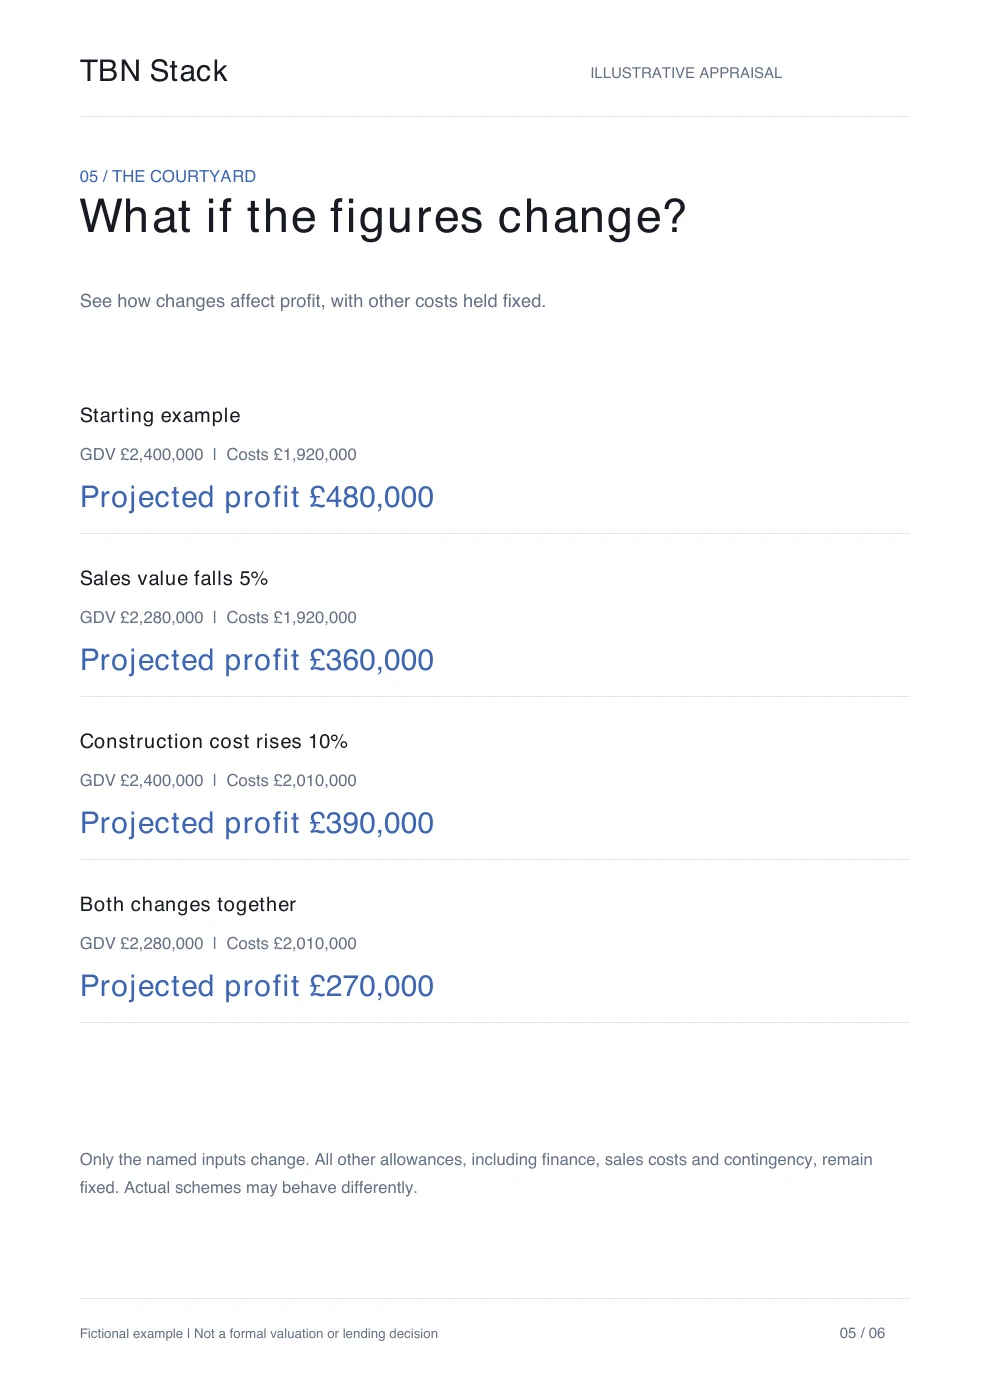
Starting example: GDV £2,400,000; costs £1,920,000; projected profit £480,000.
Sales value falls 5%: GDV £2,280,000; costs £1,920,000; projected profit £360,000.
Construction cost rises 10%: GDV £2,400,000; costs £2,010,000; projected profit £390,000.
Both changes together: GDV £2,280,000; costs £2,010,000; projected profit £270,000.
All other allowances remain fixed. Actual schemes may behave differently.
06. What still needs checking
Read this page as text
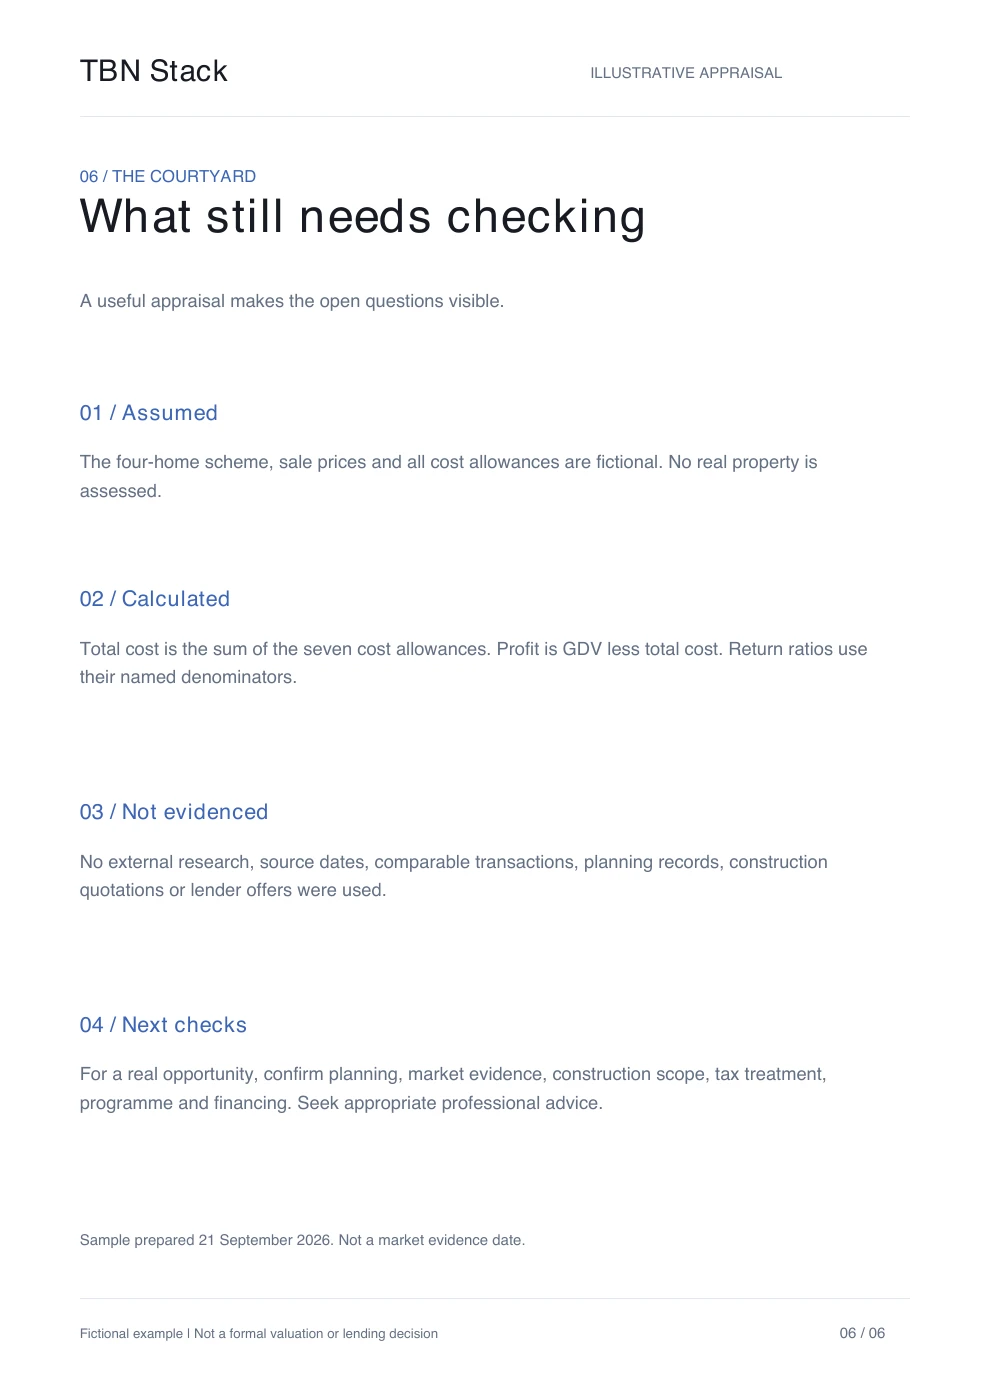
01 / Assumed: The four-home scheme, sale prices and all cost allowances are fictional. No real property is assessed.
02 / Calculated: Total cost is the sum of the seven cost allowances. Profit is GDV less total cost. Return ratios use their named denominators.
03 / Not evidenced: No external research, source dates, comparable transactions, planning records, construction quotations or lender offers were used.
04 / Next checks: For a real opportunity, confirm planning, market evidence, construction scope, tax treatment, programme and financing. Seek appropriate professional advice.